Here's a picture of Eric Schmidt (CEO of Google):
Now here's a picture of Steve Forbes:
And now here's the Head Vampire from the 80's classic, The Lost Boys:
Any questions? I think not.
Monday, December 15, 2008
Steve Forbes & Eric Schmidt Look Like the Head Vampire!



Monday, December 1, 2008
Feature Sequencing
One of the biggest mistakes I've seen companies make over the years is improper sequencing of feature sets.
For instance, if the users themselves are the hubs of a social network, then why would you launch a social networking application before giving people a reason to come to the site in the first place? That's like saying, "Hey, come to my nightclub tonight...nobody's here, you won't meet any women/men, but it'll be popular one day so just drop by and keep coming back until we get hot!"
FAIL!
I prefer to think through feature roll outs in a very methodical way -- I don't take any credit for this either, it's been done many times by many successful entrepreneurs over the years. I just happen to enjoy copying what successful people have done in the hopes of one day becoming successful as well.
In fact, I once attended a talk given by Joshua Schachter of Del.icio.us fame and he pretty much said the exact same thing I'm about to share with you...building the right features at the right time is critical to the success of a product.
In my mind this can be boiled down to a three step framework and if applied properly, could mean faster roll outs, higher quality products, greater user satisfaction and more opportunities for revenue generation.
Here's the framework in a nutshell:
Utility - First create a product that's useful for a single user. For instance, Del.icio.us was valuable long before you were able to see other user's bookmarks. In its first iteration Del.icio.us simply allowed members to store their Favorites/Bookmarks remotely, thus allowing them to retrieve these pages from any computer they happened to be on. Later on they exposed the social content discovery components that turned the service into the viral success it has become today.
Network - After you've made a product that's useful for a single person, there's a good chance that MANY individual people will find it useful. When you attract a large audience of individual users then all you have to do is pull back the curtains and allow them to start interacting with one another. It's obviously more difficult than that, but you get my drift.
Ideally you'd want it so every piece of data one of these users contributes to your site somehow adds value back to the whole network. For instance, on Del.icio.us, each time a user bookmarks a URL it adds to that URL's popularity across the system which provides all kinds of useful information for new users, visitors and members who already have that URL bookmarked. It also allows like minded people to find one another and use these new connections as a way to discover new content (e.g. if another member has a handful of the same bookmarks as me then there's a good chance I'll want to see what else he has in his favorites).
And then this leads to (hopefully) the final step in the feature sequencing framework: Revenue.
Generating revenue has become an all elusive component of this framework. I think there are a number of reasons for this but first and foremost it's because most people save this step for last while it should probably be right up there with the problem you're trying to solve.
While this may be the final step in this particular framework, it should be one of the first things a businessman thinks about. Granted, you can have a wildly successful product (and ultimately, a wildly successful business) by simply building something people love, locking them in through the network effect and allowing the revenue model to reveal itself as time goes on, but in my experience you'll dramatically increase your chances of monetary success if you think this through from the beginning and iterate on it just like you would the software.
Ultimately you'll want your utility, network and revenue models to dovetail nicely into one another - e.g. Google and contextual advertising - so it'll pay to think through this framework in a holistic manner.
What This is NOT
This is not a bullet proof way of thinking through your product development plans. It doesn't even begin to address the many nuances of conceptualizing, building and launching a product. It doesn't address user needs, market size, etc.
Simply, think of this as a "back of a napkin" way of testing your product roadmap. Conceptualize your utility, then figure out how that contributes value back to a network and then think about how to monetize that.
I know it may sound simple and probably pretty obvious, but I can't tell you how many times I've been sitting in on product development meetings and someone is pounding the table demanding that every feature plus the kitchen sink be included in "Product Version 1.0".
By testing your product roadmap against a time-tested framework like this one, you'll stand a much better shot at getting a successful product out the door in a shorter period of time, period.
Wednesday, November 26, 2008
Legacy and the Web
I know I haven't updated this blog in forever, but with good reason. We've been working our asses off at TickerHound -- I wish I could share the big secret with you now but you'll just have to wait a bit longer.
In any case, I was finally inspired to write a new post as I was on the train this morning.
I had my headphones on and two of my favorite songs played back to back:
Big Pun's: You Aint a Killer
The Notorious B.I.G's: Warning
Aside from the fact that they both have "Big" in their names (and rightfully so), the other thing these two talented artists have in common is that they've both passed away -- too young, might I add.
But here I am -- along with thousands of other hip-hop fans -- listening to these young men weave rhymes that are over 10 years old and still thinking to myself, "Damn, these guys are good". I'll be 90 years old one day (god willing) and I'll still be thinking, "Damn, these guys are good".
And that right there is the LEGACY these two men have left to this world. Their ability to take concepts, events and emotions from their lives and craft beautiful rhythmic sentences out of them.
The same applies to many creative people:
- Visual artists
- Film makers
- Actors and Actresses
But what about us?
The rough and tumble entrepreneurs who are creating, crafting and weaving beautiful web experiences and products each and every day.
Sure, we make an impact now but what about 100 years from now?
Will our works of art (read: "our web sites") even be around then? What happens if we have to close up shop and shut down our sites?
All that creative energy just fades into oblivion.
And I know what most people would say: "that's business". And while I agree to an extent I have to imagine that the web is more than just business. The very nature of it makes it so that content can persist.
Our designers and developers put just as much creative energy into building a site as a Director would into making a film -- where's their legacy?
Sure, the "Portfolio" section of a designer's personal page or an item on an entrepreneur's resume/bio gives a viewer a brief glimpse into a product that no longer exists...but don't we deserve more than that?
Shouldn't someone be able to EXPERIENCE the sites and products we've built as we originally intended? Shouldn't they be able to ask a question on TickerHound, or vote for a story on Digg or find a great wine on Snooth?
I think sites like The Way Back Machine do a decent job at preserving a site's content, but not so much the experience.
I also think sites like Blogger, Wordpress, Flickr and YouTube have also greatly helped keep legacies alive - albeit in a static form.
But I think we need a new type of web archive -- one that allows a site's experience to persist throughout time. I want my grand kids to be able to go to TickerHound (even if it no longer exists as a business) and experience something I created when I was in my 20's.
What would a "legacy" service like this even look like? How would it function? Is it even possible?
I don't know.
All I know is if there were a way to make it so a young man, 25 years from now, could use TickerHound, Digg or Snooth (whether or not the businesses were still "alive") and say, "Damn, these guys are good", then I'd be one happy entrepreneur.
Friday, October 10, 2008
Chinese Word of the Day
The US economy is going to shit and China is buying up most of our debt.
We're slowing down, they're still accelerating.
Bottom line: China is the going to be the largest economy in the world within the next generation or two, period.
Being that we operate web-based businesses that have a global reach, I think it's reasonable to assume we'll either have Chinese:
- Customers
- Investors
- or Business Partners
I grew up in Flushing, Queens here in New York:
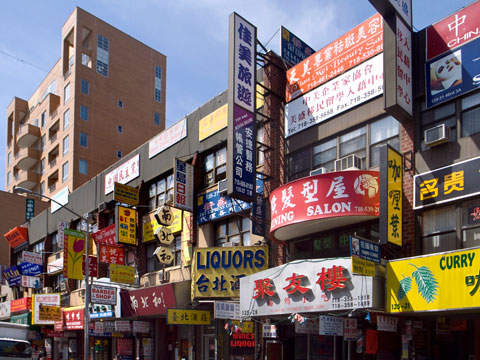
That's where I first picked up Chinese (Cantonese and Mandarin). Then I went on to Major in East Asian Studies in college where I studied Chinese for 3 years solid (spoken and written) and spent several months in China.
While I'm far from an expert, I can definitely get by.
So in the spirit of global business and global communities, I decided to start teaching Chinese one word at a time to all those who are interested.
I'll be doing this via my twitter account: @WayneMulligan
So if you'd like to pick up a new language, I'll be posting a new Chinese Word of the Day each and every day. I'll write the word out in Chinese characters, give the romanization/phonetic spelling and provide a little context.
I'm going to try and make most of the words market/business oriented but if anyone has requests or suggestions just @reply me or DM me on Twitter.
Enjoy!
Monday, September 29, 2008
Twitter Power
So I rattled off this quick Tweet this morning as I was venting over a slow net connection here at the office:
"#Sunshine Suites: These internets is running sloooow today"And then I get this e-mail from our management company a couple of hours later:
"Hey Wayne,That's some smart customer service right there!
Saw your post on twitter, let me know the details...
What seat are you sitting in and which floor?
How are you testing?
You are using ethernet?
- Jake"
Sunday, September 21, 2008
The Current Financial Mess - Simplified!
The whirlwind of news surrounding the current financial mess we’re in has my head spinning.
First it’s foreclosures, then it’s Fannie and Freddie and then it’s Merril Lynch and AIG - when will it stop?
But more importantly than that, this rapid destruction of the American financial system has many people wondering how it got started to begin with?
That’s why I decided to write this week’s article in response to this question on TickerHound:
Basically, lenders were loaning money to whoever wanted to buy a home. Credit score, income and assets became irrelevant terms as brokers and local lenders rushed to issue new mortgages.
It seemed like a relatively “low risk” strategy at the time to many banks. Reason being, they figured that even if people stopped paying their mortgages, the housing market was doing so well that folks could just sell the house for a profit and pay back the remainder of the mortgage.
And that’s really where the trouble started.
II. Then the Investment Banks Got Involved:
Mortgage Backed Securities (MBS) are nothing new on Wall Street. They’re sort of like bonds, meaning there’s a “principle amount” (the amount being loaned) and interest coupons (or payments) that would be paid monthly on the loan. However, MBS’s aren’t single loans.
Instead, these loans were really thousands of individual mortgages all pooled together to create a single, tradable security.
This is another reason why many lenders were happy to keep giving out mortgages to folks (even if they didn’t qualify). Local lenders knew that they’d be able to package up all those mortgages and just sell them right to the big investment banks and not have to worry.
The banks then turned around and would trade these Mortgage Backed Securities like they would a stock or a bond - trying to pocket profits in between each trade.
III. Bubbles
The basic assumption in this whole mess was that housing prices would continue to rise each year.
In fact, that assumption turned out to be pretty accurate. According to the S&P Case-Schiller Index, home prices nearly doubled across the country from 2001 - 2006.

That’s because it was so easy to get a mortgage, everybody wanted to buy a home. Thus spurring demand and in turn driving up prices further. It sort of became a self fulfilling prophecy, which in turn became a full-fledged housing bubble.
And just like any good bubble, it eventually had to pop!
IV. The “After-Pop”
So after the housing market finally started to tumble, the financial services industry went into a year-long death spiral. Here’s the basic sequence of events:
- People couldn’t afford their mortgages anymore.
- They couldn’t sell their homes for more than they paid due to falling prices
- So they defaulted on their loans - this happened to millions of people!
- The big investment banks which now owned all the mortgages suddenly realized that these “assets” were virtually becoming worthless in a very short period of time.
- So the banks had to take massive write-downs on these loans. The way this works is the banks were considering these baskets of mortgages as assets on their balance sheets. Once the assets went from being worth $100 to $1, the banks basically lost 99% of their value.
- When that happened it made it very difficult for the banks to get loans themselves (imagine applying for a loan when all you have is a pack of bubble gum and the clothes on your back - it’s not likely to happen).
- When the banks couldn’t get their own loans they were either going to be forced into bankruptcy (Lehman Brothers) or had to be swallowed up by healthier firms (Bear Stearns, Merrill Lynch, etc.)
V. How the Government Got Involved
Ever since Bear Stearns went under the government has played a fairly prominent role in this whole mess.
But it wasn’t until we almost saw the implosion of Fannie Mae and Freddie Mac that the government really made its presence felt.
Fannie Mae and Freddie Mac are sort of like “buyers of last resort” in the mortgage market. They were established to maintain liquidity in these markets in the event of the large banks being unable to trade their Mortgage Backed Securities.
So in the end, Freddie and Fannie were sitting on trillions of dollars in bad home loans.
And while these companies were private organizations they were however government sponsored organizations. So if the government had let either one of these companies fail then it might’ve made it very difficult for the United States to keep selling debt to big foreign buyers, like China. Remember, it’s our ability to sell our debt to other countries that has been funding our country’s operations (e.g. wars, etc.) for the last several years.
VI. How AIG and Insurance Fit In
AIG came into the picture when it began selling “insurance” to the big banks.
This technically wasn’t insurance, but that was mainly due to clever wording on the part of AIG management. Because for all intents and purposes, they were basically insuring the mortgages held by the banks - this type of insurance was called a “Credit Default Swap”, or a CDS.
Basically, the banks would pay AIG a monthly fee and in turn AIG would promise to make the bank whole on any mortgages that defaulted (sure sounds like insurance to me).
At the time I’m sure this sounded like a good idea because everybody assumed housing prices would continue to rise.
Well we all know how that turned out and that’s why in the end AIG was left holding the bag for billions of dollars in bad loans.
VII. The Bailout
So that brings us to where we are today: On the eve of the largest government bailout of the private sector in the history of this country.
The implications for these actions are vast and complex.
On the one hand, the government has to do this; the alternatives are too disastrous to even comprehend. On the other hand, what type of message does this send to the banks going forward? That it’s ok to engage in risky, reckless behavior and they’ll always get bailed out in the end?
I think I’ll save the rest of my commentary for another post.
I hope this gives you a clear picture of why and how we got into our current predicament.
If you have any other questions on this topic feel free to go to TickerHound for the answers!
Thursday, August 28, 2008
The China Adventures...Finally!
I know, I know, I promised to post these 2 months ago but I've got a good excuse.
TickerHound's been going surprisingly well this summer and it's been monopolizing the vast majority of my time. So now my blog AND my girlfriend hate me and my entrepreneurial spirit :(
j/k
In any case, here are my pics from June's trip to China...we had an AMAZING time!
Beijing is much cleaner than it was 3 years ago, but it also lost some of its "edge". There were no more gypsy cab drivers at the airport trying to drag me into their overpriced cabs, no more fake DVD's being sold on the streets of Beijing and my white T-shirts didn't turn brown from the rain anymore.
I guess some would call this progress, but for me, I missed my Beijing funk.
Don't get me wrong, there were still some funky sights to be seen, but China definitely got its act together for the Olympics.
Shanghai was great too, but then again, it always has been. I think on my next trip to China I'm staying out of the cities and heading into the countryside. It's high time I see what the vast majority of the country lives like, not just the wealthier (comparatively speaking) city folk.
So without further ado, heeeeeeere's China!

This was my friend Winston's wedding. His wife's mother was one of the higher ups at China's CCTV. Therefore, there were more people manning cranes, cameras and fog machines than there were guests!
Great wedding though! Congrats again Winston!
 Who's ready to drink??

My boy Mao lives here.

I don't know why but I thought these outdoor, branded food/drink kiosks were so cool.
 A spot of tea?
And now for the food!


I'll post more pics soon enough...this just made me reeeeeally hungry!
Subscribe to:
Posts (Atom)

